Brendon’s Eye on New York: Are Condos the New Co-Ops?
2026
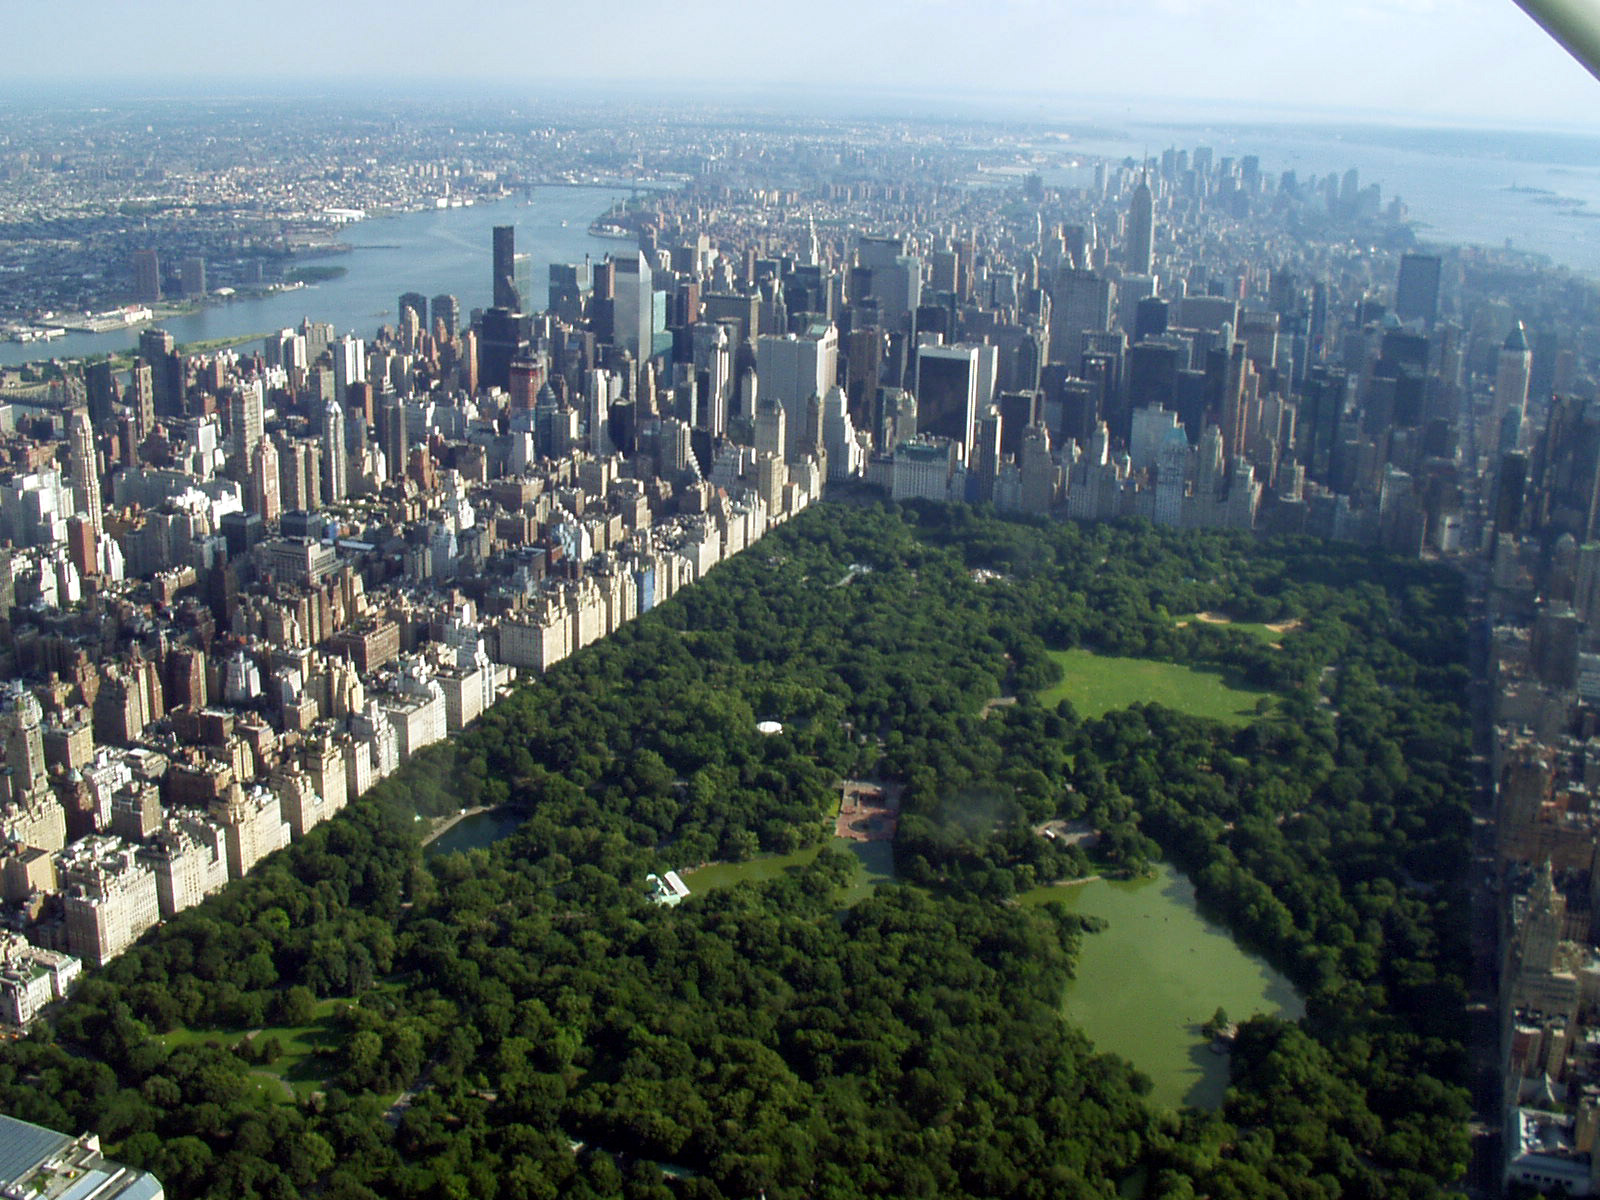
Unlike San Francisco and most U.S real estate markets, New York real estate is dominated by cooperative apartments, or Co-Ops. Whether you’re a regular Joe or a famous film star, to buy a Co-Op you must go through a demanding process. This includes handing over every piece of financial data, providing both personal and business references and being interviewed by the board of directors of the Co-Op. The Co-Op board can reject a buyer for any reason. As an owner, you are subject to a variety of rules and restrictions. For example, in some Co-Ops owners are not allowed to rent out their apartments.
The emergence of condos has provided an alternative to buyers who don’t want to jump through the Co-Op hoops. However, as a result of the economy and homeowners falling behind of monthly assessments, many condo boards now require new buyers to be “approved”, and they’re putting them through the ringer. Though they don’t have the authority to reject a potential buyer or renter, like a Co-Op board, they can make it increasingly difficult by dragging out the process. The only recourse a condo board has is to purchase the condominium, if they feel the condo owner is not selling it for the best price. So, if you’re looking to avoid the hassle of the Co-Op, be prepared for “less” hassle with a condo.
Outside of New York, a new condominium buyer never interfaces with the homeowners association, property manager or managing agent. The seller accepts a buyer’s offer and that is it. The number of layers and parties involved in a New York purchase can be overwhelming, making a purchase difficult to navigate.